


Director General of Taxes Regulation PER-12/PJ/2026 concerning Amendments to Director General of Taxes Regulation Number PER-11/PJ/2025 concerning Provisions for Reporting Income Tax, Value Added Tax, Sales Tax on Luxury Goods, and Stamp Duty in the Context of the Implementation of the Core System of Tax Administration (Coretax)
- October 12, 2026
- Posted by: Bella Rachmafanny
- Category: Tax Updates

PER-12/PJ/2026 was issued to adjust the tax reporting provisions with the implementation of Coretax, especially related to the delegation of Withholding Tax (WHT) slip signatures, tax return correction mechanisms, compensation for overpayment, and provisions for reporting Periodic VAT Returns and Annual Tax Returns.
Important matters that require attention include:
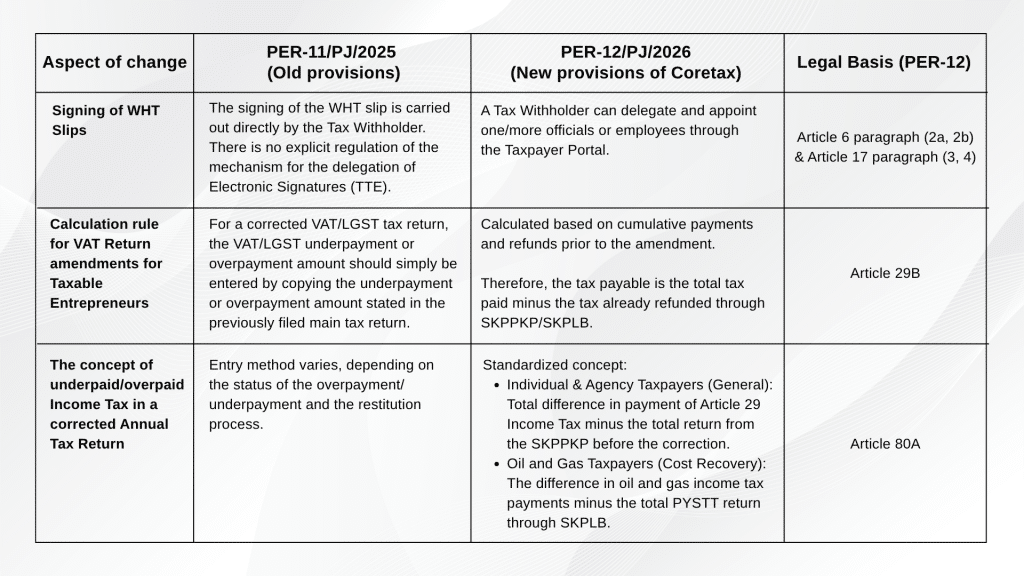
- Signature delegation of WHT slips
A Tax Withholder can appoint one or more officials/employees to sign the WHT slips forArticle 21/26 Income Tax and Unification Income Tax through the Taxpayer Portal. - Changes in the calculation of tax return correction involving tax refunds
The calculation of Underpayment or Overpayment on Amended Tax Returns (applicable to Article 21 Income Tax, VAT, and Individual/Corporate Annual Income Tax) has been updated. It is now based on the accumulated taxes paid, less any tax refunds already issued. This change aims to eliminate the risk of an “incorrect underpayment” status which fails to reflect the actual tax payment position within the system. - Automatic overpayment compensation adjustment
Any changes to the compensation balance resulting from an amended return or a tax audit will be automatically adjusted in the Normal Periodic Tax Return for the next tax period. Consequently, Taxpayers are no longer required to perform repeated amendments for subsequent periods. - Reporting of Periodic VAT Returns must be sequential
A Periodic VAT Return with Normal status cannot be reported if the previous period’sPeriodic VAT Return has not been reported. Exceptions apply if the previous tax period is under open audit. - Special provisions for correction of Annual Tax Returns
The correction of an Annual Tax Return for Individual and Corporate Taxpayers will stop the preliminary investigation and/or examination process in the context of restitution. In addition, the approval of instalment payments or postponement of the payment of Article 29 Income Tax becomes invalid if the Annual Tax Return is corrected. - Changes in the calculation of Under/Overpaid Income Tax
For Individual and Corporate Taxpayers, the value of Article 29 Income Tax on the corrected Income Tax Return is calculated based on the total payment of Article 29 Income Tax minus the refund of overpayments that have been issued before the correction. Special provisions apply to Oil and Gas Taxpayers with the Cost Recovery scheme.
To make it easier to understand the changes from the previous provisions, the following is a comparison table of PER-11/PJ/2025 and PER-12/PJ/2026:
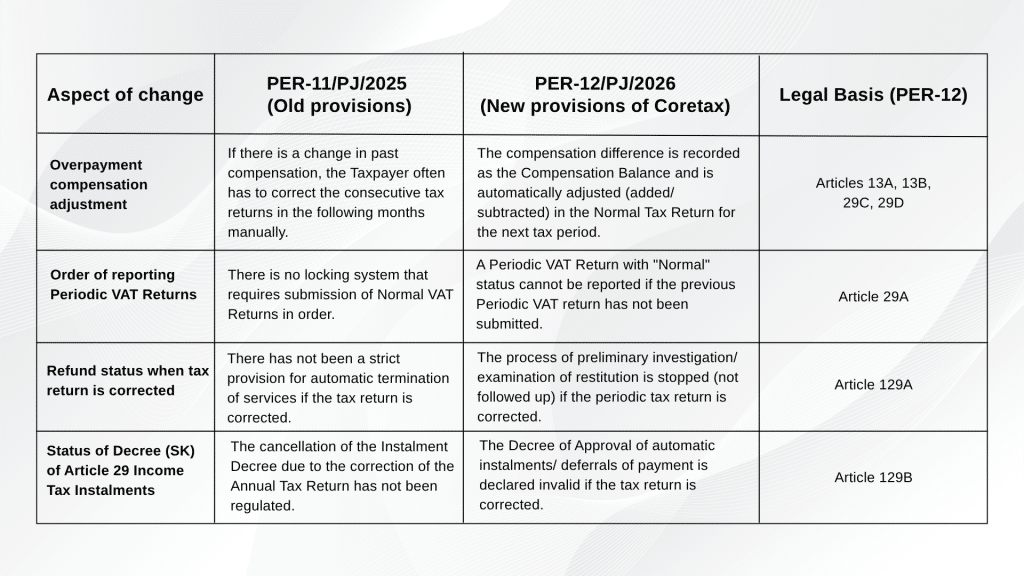

However, alongside these improvements, the new system also requires greater discipline and compliance. Periodic VAT Returns must now be filed sequentially. In addition, automatic consequences may apply, including the suspension of ongoing tax refund processes and the invalidation of an Instalment/Tax Deferral Approval Letter (Article 29 Income Tax) if the taxpayer submits a tax return correction.
These regulations took effect on October 1, 2026.
Transition Period:
Tax return amendments or filings submitted prior to October 1, 2026 will be processed under the previous regulation (PER-11/PJ/2025), while those submitted on or after October 1, 2026 must comply with PER-12/PJ/2026.


